How to choose an unsecured SME loan in Singapore
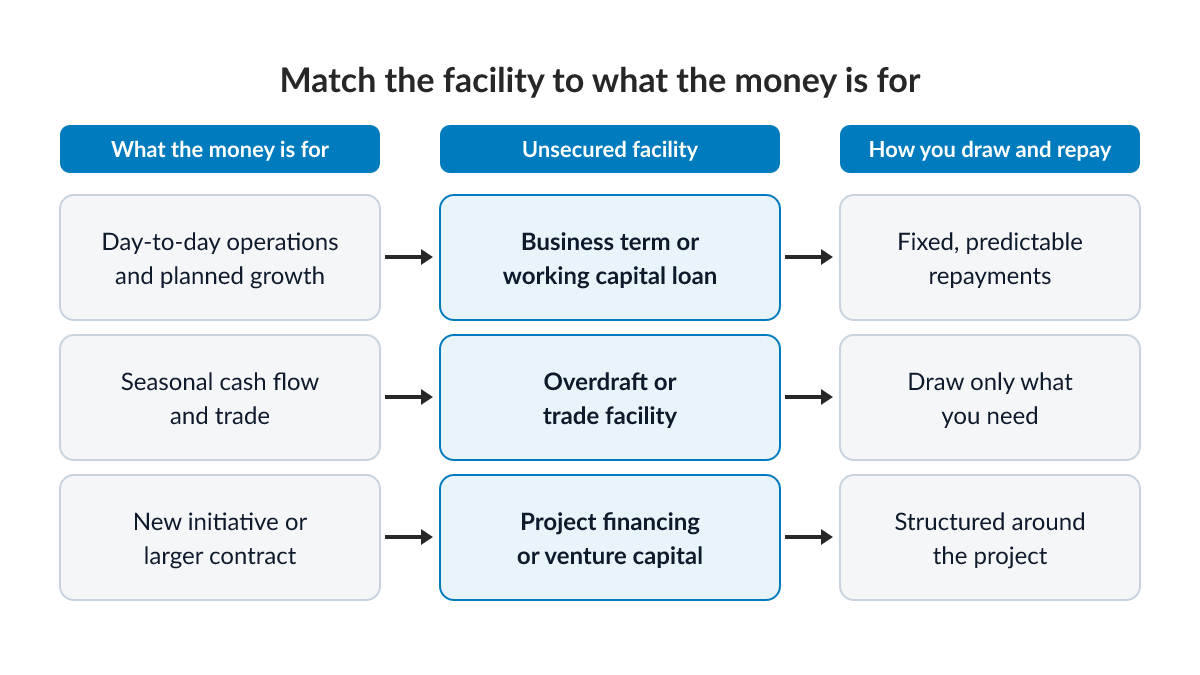
An unsecured business loan can support working capital, expansion, trade or a new project without requiring property or equipment as collateral. The important decision is not simply whether funding is available, but whether the facility, repayment structure and total cost suit the cash-flow need it is meant to solve.
Secured or unsecured: which fits your need?
| Consideration | Unsecured financing | Secured financing |
|---|---|---|
| Collateral | No business asset is pledged as security, although guarantees may still be requested. | A specific asset or receivable supports the facility. |
| Typical fit | Working capital, shorter-term growth needs and time-sensitive opportunities. | Larger or longer-term requirements where suitable security is available. |
| Assessment focus | Trading history, cash flow, credit profile and ability to repay. | Those factors plus the quality and value of the security. |
| Trade-off | Less asset documentation, but pricing and limits reflect the lender's risk assessment. | Security can support different limits or terms, but the asset is exposed if obligations are not met. |
If your requirement is backed by invoices or another eligible asset, compare it with secured financing before deciding. Businesses waiting for customer payments can also review our plain-English guide to invoice financing.
Government-assisted working-capital loans
Government risk-sharing may support eligible facilities, but the application is still assessed by participating financial institutions. Eligibility does not guarantee approval, and the lender's credit assessment and facility terms still apply.
What lenders assess
- Business history and sector
- Recent financial performance and bank conduct
- Existing commitments and repayment capacity
- Credit profile of the business and guarantors
- Purpose and requested facility size
How Ascent Consultancy arranges a facility
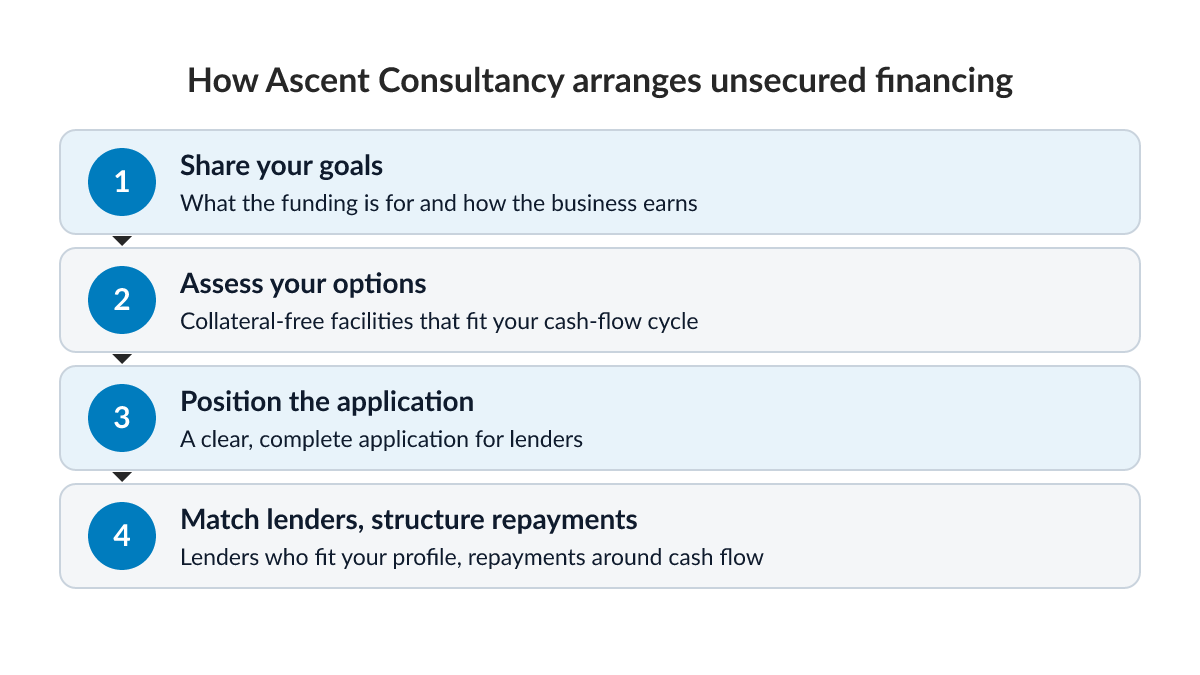
- Clarify the requirement. Define the funding purpose, amount, timing and acceptable repayment load.
- Review the business profile. Check the information lenders are likely to rely on and identify gaps before submission.
- Compare suitable routes. Consider lender fit and facility structure instead of treating every offer as interchangeable.
- Support the application. Present the required information clearly and help the business understand the terms before proceeding.
Five questions to ask before you sign
- What is the total cost of the facility, including fees?
- Is the repayment schedule aligned with when cash enters the business?
- Are personal guarantees or other commitments required?
- What happens if payment is late or the facility needs to be restructured?
- Would a different facility — such as invoice financing or a secured loan — fit the use of funds better?
When an unsecured loan may not be the right answer
- The business needs long-term capital but can only support short repayments.
- The funding purpose does not create or protect enough cash flow to service the instalments.
- A secured or invoice-backed facility could be better matched to the underlying asset or receivable.
- Existing commitments already leave too little headroom for a new obligation.
For a wider comparison, read secured versus unsecured financing. If timing is the primary concern, review the factors behind a faster business-loan application. Businesses considering support beyond financing can also explore grant advisory.